Paysafecard availability does not establish that an offshore casino is authorised to offer real-money games in Australia.
A payment method does not determine whether an online casino service may lawfully be offered in Australia. A site describing itself as Australian, accepting Australian customers or displaying a payment option associated with Australia is not thereby authorised to provide real-money casino games to people in the country. The legal question is about the service and its intended customers, not the label attached to a cashier.
The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people physically located in Australia. The prohibition covers casino-style services such as pokies, poker and table games. It applies even when an operator is based overseas or presents its business as an offshore casino. For this legal distinction, the operator’s location does not convert a prohibited service into a lawful one for customers in Australia.
That makes phrases such as “Australian online casino” potentially misleading. They may refer to a website aimed at Australians, rather than a casino authorised under Australian law. The phrase “pokies that accept paysafecard” also combines two separate matters: the legal status of offering online casino games to people in Australia, and the payment arrangements a site may describe. A payment option cannot change the legal status of the underlying service.
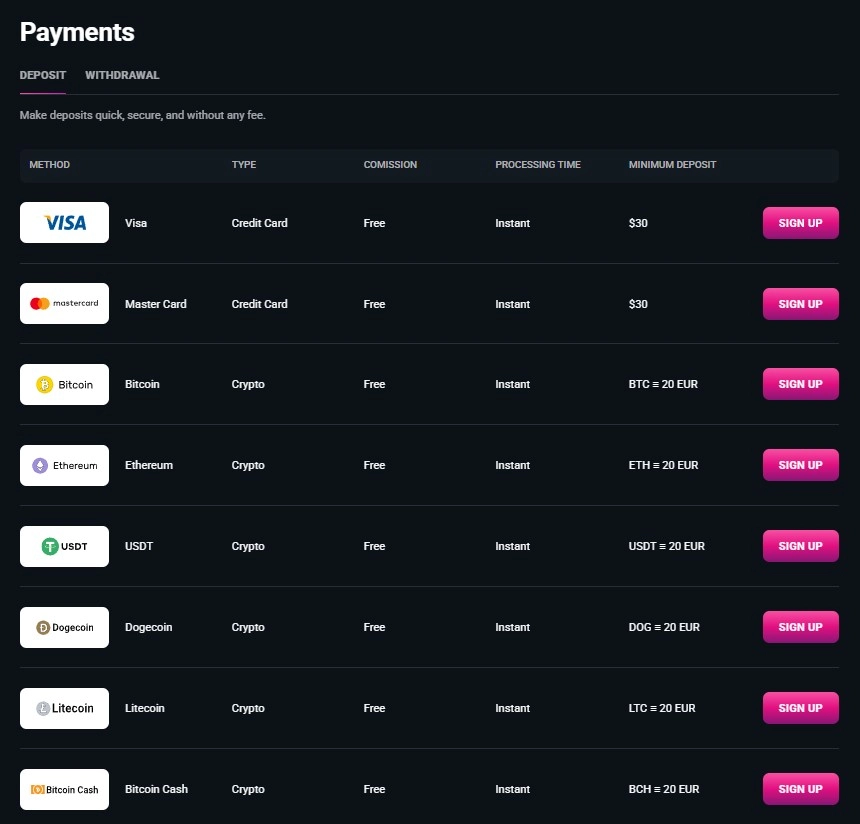
For Australian players considering casino sites that accept paysafecard, payment availability and the terms attached to each option are important to check. This list provides a brief reference based only on the available operator details.
Bizzo Casino
Bizzo Casino is identified as licensed by the Curacao Gaming Control Board, with TechSolutions Group N.V. named as the license holder.
Vegaz Casino
Vegaz Casino is listed under Curacao OGL/2024/1335/0780. Its stated minimum deposit is EUR 20.
Neospin
Neospin is listed under Curacao Gaming Control Board license OGL/2023/176/0095, held by Hollycorn N.V.
Ricky Casino
Ricky Casino lists crypto payouts in under an hour and PayID payouts in 1–3 business days. The minimum deposit is A$20, or A$30 to qualify for the bonus.
7Bit Casino
7Bit Casino is identified as a Curacao casino operated by Dama N.V.
Kingmaker
Kingmaker lists crypto payouts at around 90 minutes and fiat payouts in 1–5 days. Its stated minimum deposit is A$30.
WinSpirit Casino
WinSpirit Casino is listed under Curacao eGaming license OGL/2024/923/0383, associated with Antillephone N.V. Its minimum deposit is A$30.
Playfina Casino
Playfina Casino is identified as a Curacao eGaming casino operated by Hollycorn N.V. since 2017. Its minimum deposit is A$20–30, depending on the offer.
Golden Pokies
Golden Pokies is identified as a Curacao casino; no further operator details are available here.
DragonSlots Casino
DragonSlots Casino is identified as licensed by the Curacao Gaming Authority and operated by Jumpman Gaming Ltd.
The Act is directed at operators. It makes providing the prohibited service to people in Australia unlawful; it does not explicitly make an individual player’s use of an offshore site a criminal offence. That distinction should not be mistaken for approval, a guarantee of access or a statement that an offshore casino is protected by Australian regulation. It simply separates the legal rule imposed on operators from the position of a player using such a site.
The regulator responsible for administering enforcement of the Interactive Gambling Act is the Australian Communications and Media Authority, commonly shortened to ACMA. Its role concerns compliance with the law, rather than endorsing particular websites or payment methods. A site’s claim that it accepts Australian customers, or that it supports a particular way to pay, is not evidence of ACMA approval.
The legal framework also affects how online casino services can be presented to Australian audiences. Real-money interactive gambling services, including online casinos, cannot be advertised to that audience. Accordingly, a list framed as the “best” Australian paysafecard casinos would risk presenting access to a prohibited service as a recommendation. No payment detail can make that framing appropriate.
There is a practical distinction between being able to find a website and the legal status of the service it offers. Offshore casino services are actively subject to blocking and enforcement in Australia. A page that loads, a cashier that displays a payment option, or a promotional claim about Australian customers does not establish that the operator may lawfully serve people in Australia. Nor does the availability of a payment method establish that a transaction will be accepted or that the site has local authorisation.
The wording around online pokies often blurs these distinctions. “Australian” can describe the audience a site seeks, the currency it displays, or the country named in its marketing; none of those descriptions is equivalent to a domestic licence to provide real-money casino games. “Accepts paysafecard” is a claim about payment acceptance, not a legal status. In Australia, the prior issue is that operators may not offer real-money online casino games to people physically here.
This is why a payment search cannot be treated as a shortcut to a lawful casino option. Paysafecard, cards, bank-linked services and other payment methods sit outside the core legal test: whether an operator is providing a prohibited online casino service to Australian residents. The payment method does not create an exception to the Interactive Gambling Act, and a website’s own wording cannot create one either.
For legal context, the relevant points are therefore narrow but decisive: the Act prohibits operators from offering real-money online casino games to people in Australia; ACMA is the body responsible for enforcement; and the Act does not explicitly criminalise players for using offshore sites. Those points describe the framework, not an endorsement of offshore access or a recommendation to use any casino service.
A stated deposit amount and the full cost of a payment are separate figures. The amount entered for a transaction describes its intended value; it does not, by itself, establish whether a payment method is available, what will be charged, or whether a transaction can be completed. That distinction matters when assessing a proposed $10 paysafecard deposit in Australia: the figure is a nominal amount, not proof of the payment terms attached to it.
The arithmetic is simple, but the conditions are not interchangeable. A $10 entry cannot establish a minimum deposit, a fee, a processing result or the amount ultimately accepted by a service. Those are separate terms. Treating the entered figure as confirmation of all of them turns a search phrase into a financial assumption.
The $10 wording identifies the amount being considered. It does not identify the currency unless the transaction specifies one, nor does it say whether a payment service accepts that denomination. In an Australian transaction, an amount intended to be in Australian dollars should be distinguished from any amount denominated in another currency. A displayed figure and a final charge are not automatically the same thing.
A careful comparison would keep the elements separate:
The first item can be stated as $10. The remaining items cannot be inferred from that number. Combining them into a single claim such as “a $10 deposit is available” gives the amount more meaning than it carries.
This also applies to searches for a casino deposit by paysafecard or a casino that accepts paysafecard deposits. Such wording expresses an interest in using a payment method for a particular transaction. It is not evidence that a service provides that option, or that the same terms apply across different services. A payment label alone is not a complete price.
A payment decision depends on the applicable terms, not only on the figure placed in an amount field. Any additional charge would change the total cost; a currency difference could also affect what is paid. Neither outcome can be calculated from the nominal amount alone. The sensible accounting treatment is to keep the requested amount and the final payable amount as separate lines until the transaction terms are known.
That is not a paysafecard-specific promise or a claim about how a particular cashier works. It is the basic distinction between an amount someone intends to pay and the amount a transaction actually costs. A $10 figure cannot establish a fee-free payment, a particular exchange rate, or successful processing.
Nor does a low stated amount establish that a transaction is legally available. In Australia, the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people located in the country. That prohibition covers casino-style services regardless of whether a proposed payment is small or large, or which payment method is mentioned. A payment option does not alter the legal status of the underlying service.
The law is directed at operators; it does not explicitly criminalise an individual for using an offshore site. That does not make offshore casino use a protected or authorised consumer transaction. Australian consumer law does not protect players who use offshore casinos, and access to such services is subject to blocking and enforcement. The amount in a payment search does not change those limits.
Statements about a paysafecard deposit should be read narrowly. “Accepts paysafecard” concerns payment-method availability; “$10 deposit” concerns a proposed amount. Neither statement, on its own, establishes the other. A service might describe a method without confirming that a particular amount can be used, while an amount displayed in a search result would not confirm that the named method is supported.
The same separation prevents misleading comparisons. A “best” label does not supply a price, verify a deposit condition, or demonstrate legal suitability for Australian residents. Rankings and promotional wording are not substitutes for transaction terms. More importantly, no comparison should be treated as an invitation to use an online casino service that Australian law prohibits operators from providing locally.
For a sound calculation, the amount, currency, payment method and any stated charge must be identifiable as distinct terms. If one of those elements is unknown, the total cannot be reliably derived from the number alone. The $10 search describes a figure under consideration; it does not settle the cost, availability or legality of a casino transaction in Australia.
A deposit and a withdrawal are separate transactions. The first concerns money moving into an account; the second concerns money being paid out. A claim about one does not establish anything about the other. In particular, the word “instant” attached to a paysafecard deposit cannot be carried over to a withdrawal without evidence about the payout route, processing steps and applicable terms.
The same distinction applies when a payment method appears alongside searches for real-money play or Australian pokies. A payment option does not establish that an operator can lawfully provide online casino games to people in Australia. Under the Interactive Gambling Act 2001, operators are prohibited from providing real-money online casino games to people physically located in Australia. The legal status of the service is separate from the mechanics of a payment transaction.
“Instant withdrawal” is not a complete description of a payment. It could refer to the time an operator takes to approve a request, the time a payment service takes to process it, or the point at which funds become available to the recipient. Those stages are not interchangeable. A statement about one stage cannot establish that the full withdrawal is immediate.
For a paysafecard-related payout, a meaningful timing claim would need to identify the actual withdrawal method and the relevant processing conditions. It would also need to distinguish operator review from payment processing. Without those details, “instant” is a label rather than a measurable term. No particular paysafecard withdrawal route or timing can be inferred from the payment method’s name alone.
This matters even where a cashier displays a payment option for deposits. A listed deposit method does not prove that the same method is available for withdrawals, that winnings can be returned through it, or that a payout will follow the same path as the incoming payment. Deposit acceptance and withdrawal support are separate conditions, not two descriptions of one transaction.
A phrase such as “no deposit” concerns whether a deposit is required for an offer or account condition. It does not, by itself, define how a withdrawal is requested or processed. Nor does it establish that a payout is available, that a particular payment method can receive it, or when funds would arrive. These are distinct terms and should not be collapsed into a single promise of immediate access to money.
The same applies to real-money wording. It describes the kind of activity being sought, not the legality of the service or the speed of a payment. In Australia, the relevant prohibition concerns operators providing online casino games to people in the country. A payment descriptor cannot alter that rule or turn an unlawful service into a lawful one.
Offshore access should not be treated as a substitute for a locally regulated casino service. Australian consumer law does not protect players who use offshore casinos, and the Australian Communications and Media Authority enforces the Interactive Gambling Act. These are material limits, not minor qualifications to a payout estimate.
Accordingly, a search for an instant paysafecard withdrawal in Australia cannot produce a reliable timing figure on its own. Any genuine timing term would have to specify the payment route and the stages covered, while the legality and consumer-protection position would remain separate issues. Where those conditions are not established, an exact arrival time is not a calculation; it is an unsupported promise.
A paysafecard-accepting casino is, in ordinary payment terms, a casino operator that lets a customer use paysafecard when paying. The phrase describes a claimed relationship between a payment method and a service. It does not, by itself, establish what transactions are supported, what conditions apply, or whether the service may lawfully be offered in Australia.
That distinction matters because “accepts” can be used loosely. It might refer to a payment option appearing in a cashier, or to a transaction being accepted under particular account conditions. The label alone does not establish that a payment will be approved, what it can be used for, or whether the option is available to every customer. A payment-method logo or a general statement of acceptance is not a complete set of terms.
Nor does payment acceptance amount to a finding that an operator is authorised to provide online casino services in Australia. Under the Interactive Gambling Act 2001, operators may not provide real-money online casino games to people physically located in Australia. The Australian Communications and Media Authority enforces that law. The legal position concerns the service itself, not the payment method selected for it. A different cashier option cannot change the status of the underlying activity.
This is why “casino sites that accept paysafecard in Australia” should not be read as a list of locally lawful services. Offshore services may present payment claims, but their availability or payment arrangements do not establish Australian approval. Offshore casino players are not protected by Australian consumer law in the same way as consumers dealing with services covered by that law. A payment label is not a substitute for that protection.
The wording “paysafecard debit” also needs care. A search phrase may use “debit” to distinguish a payment from a credit-card transaction, but that wording does not confirm how a particular operator classifies paysafecard or what transaction types it supports. The terms attached to the payment option would need to specify those details. Without such terms, “accepts paysafecard” remains a broad description rather than a precise statement of service.
For a meaningful comparison, acceptance would need to be defined narrowly: which transaction is involved, which account conditions apply, and which rules govern the service. Those are separate questions. A method might be mentioned in connection with an operator without proving that it can be used for every payment purpose. Equally, payment compatibility says nothing about game availability, account status, or Australian legal compliance.
There is no useful ranking hidden in the word “best”. A payment method alone cannot establish that one casino is better or suitable for Australian residents. That would require reliable information about the service and its terms, as well as a lawful basis for offering it in Australia. Where online casino provision to people in Australia is prohibited, presenting an offshore operator as a recommended option would misstate the central issue.
So the phrase “paysafecard-accepting casino” has a limited meaning: it signals a claimed payment-method connection. It does not prove that a transaction will work, that all payment conditions are clear, or that the casino may serve customers in Australia. The payment label answers only one small question; it does not settle the legal or consumer-protection questions around the service.
A paysafecard reference alongside casino slots combines two separate questions: whether a payment method is accepted and whether an operator may provide the game in Australia. The wording does not answer either question. In particular, it does not establish that a particular website accepts paysafecard, that a deposit would be processed, or that a slot-style game may lawfully be offered to someone in Australia.
The legal distinction matters more than the payment label. Under the Interactive Gambling Act 2001, operators are prohibited from providing real-money online casino games to people physically located in Australia. Slot-style games fall within that category. A payment method cannot change the status of the service: describing a site as paysafecard-compatible does not make its casino games lawful to provide in Australia.
Terms such as “best” or “top” also do not supply a reliable basis for comparison. They may appear beside claims about payment acceptance, game selection or promotional offers, but those are different conditions. A page that mentions paysafecard and slots together does not, by that wording alone, confirm a working payment route, establish the availability of any particular game, or demonstrate that the underlying service can be offered to Australian residents.
Bonus language requires the same separation. A reference to a paysafecard casino bonus is not proof that an offer exists or that any stated conditions are complete. More fundamentally, promotional framing does not alter the restriction on providing real-money online casino games in Australia. Casino advertising is also subject to Australian restrictions, so bonus claims should not be treated as a neutral guide to available services.
The term “slot” can refer broadly to a digital casino game, while “paysafecard” names a payment method. Putting the words together does not show that the method is accepted for that game, that it can be used for a financial transaction, or that the game is available under Australian law. Each claim would require its own current confirmation; none follows automatically from a search result title or a site’s general payment wording.
A payment method is not permission to provide a prohibited service; combining a payment method with slot games does not establish lawful availability or promotional eligibility in Australia.
A list of paysafecard slot sites would imply that operators are being identified as options for Australian residents. That would turn a payment-and-game phrase into a recommendation, despite the legal restriction on operators providing these games in the country. The distinction is not cosmetic: a payment method is not permission to provide a prohibited service.
For an Australian audience, the relevant reading of these combined terms is therefore limited. They describe an interest in the overlap between a payment method and online slot-style games, but they do not establish lawful availability, payment acceptance, or promotional eligibility. The presence of paysafecard in a description cannot resolve those separate issues, and a “best” label cannot substitute for them.
A reference to paysafecard alongside casino games combines two separate questions: what a payment method is used for, and whether a particular service may lawfully offer games to people in Australia. One does not answer the other. A payment label cannot establish that a game is available, that a transaction will be accepted, or that the service is permitted to operate in this market.
The distinction matters because real-money online casino games are prohibited services when offered to people physically located in Australia. The restriction covers casino-style games such as poker and table games, not just one category of game. Describing a site as accepting a payment method does not change the legal position of the service or turn its games into permitted offerings.
“Paysafecard payment for casino games” is therefore not a complete description of a transaction. It leaves out the operator, the terms attached to the payment method, and whether the relevant service can legally be offered in Australia. It also does not establish that a payment method can be selected for every game or that game-specific payment rules exist. Those are separate matters, not consequences of putting a game and a payment name in the same phrase.
The cashier is the relevant place for a service to state which payment methods it supports and on what terms. But a displayed option is not a substitute for assessing the service itself. Payment availability does not establish approval under Australian law, nor does it confer consumer protection on someone using an offshore casino. Australian consumer law does not protect players who use offshore casinos.
This separates the commercial wording from the material issue. A payment method concerns how a transaction may be handled; the game concerns what the operator is offering. Neither should be treated as evidence for the other. In Australia, the legal status of the casino service remains decisive, regardless of the payment wording attached to it.
A paysafecard deposit and a withdrawal to paysafecard are separate payment functions. A method appearing among deposit options would establish only that it can be used to fund an account under the stated terms. It would not, by itself, show that the same method can receive a payout.
That distinction matters when interpreting claims about a casino with paysafecard withdrawals. “Paysafecard accepted” can refer only to deposits; it does not specify the direction of a transaction. Nor does a successful deposit demonstrate that winnings can be returned through the same route. Treating the two as interchangeable turns an unverified assumption into a financial expectation.
A withdrawal route requires its own terms. Those would need to identify whether paysafecard is available for payouts, any eligibility conditions, and how the transaction is handled. Without those details, the label alone cannot establish a paysafecard withdrawal option, its availability to an Australian customer, or the conditions attached to it. No particular route or processing arrangement can be inferred from the payment method’s name.
The wording “online casino withdrawal on paysafecard” therefore describes a specific outcome, not merely a deposit facility. The same applies to references to paysafecard withdrawals for pokies: the game category does not resolve how money can leave an account. A payment method and a game label answer different questions.
A useful distinction is between the funding method shown before a transaction and the payout method actually permitted for a withdrawal. They may match, but that cannot be assumed. An account balance, a deposit record, or a general acceptance statement does not settle the payout question.
In Australia, this payment distinction does not change the legal status of the underlying service. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people physically located in Australia. Descriptions of deposit or withdrawal functionality should not be read as an offer or endorsement of such services.
The narrow conclusion is that paysafecard deposit support does not prove paysafecard withdrawal support. A claim about the latter needs explicit terms addressing payouts; absent those terms, the withdrawal route remains unestablished.
“Paysafecard accepted” can describe a payment option shown by an operator, but the label alone does not establish what a transaction would involve. It does not confirm that the method is available to a particular customer, that a payment would be approved, or that the same option applies to every account or transaction.
Acceptance also has a narrow meaning. It concerns whether a payment method is presented for a specified purpose; it does not, by itself, say anything about other parts of an account. In particular, a deposit method and a route for receiving funds are separate matters. A reference to paysafecard cannot be treated as proof of a paysafecard payout, nor does wording about a payout establish that deposits are supported.
The phrase “paysafecard casino” therefore compresses several different questions into one. It may refer to a payment option, the conditions attached to a transaction, or an assumption that the method works for both funds going in and funds coming out. Those are not interchangeable claims. A general acceptance label does not settle transaction eligibility, account-specific restrictions, or the terms that apply at the point of payment.
The distinction matters because a payment logo or a brief method description is not a complete set of terms. Without transaction-specific information, it cannot establish the processing outcome or any conditions attached to it. The same caution applies to descriptions of games that supposedly pay directly through a particular method: a payment-method label alone says nothing about game outcomes or the route by which funds might be received.
For Australian readers, naming a payment method does not make an online casino service lawful or amount to a recommendation to use one. The phrase “casino sites accepting paysafecard” should be read as a claim about payment support, not as evidence of overall suitability, availability, or a complete deposit-and-payout arrangement.
A payment method does not determine whether an online casino can lawfully serve people in Australia. Whether a site presents itself as Australian, accepts a payment method associated with Australia, or processes a payment in Australian dollars does not change the legal position of the service.
Under the Interactive Gambling Act 2001, operators cannot provide real-money online casino games to people physically located in Australia. This applies to casino-style games regardless of how a deposit is made. The Act does not explicitly make it a criminal offence for an individual to use an offshore casino, but that distinction does not make the service locally regulated or protected.
The Australian Communications and Media Authority (ACMA) enforces the Act. Offshore casino services are subject to blocking and enforcement measures; a site appearing online is not evidence that it has approval to operate in Australia.
Australian consumer law does not protect players who use offshore casinos. If a dispute arises over an account, payment, or winnings, the protections available for a locally regulated service cannot be assumed to apply. The operator may be outside the practical reach of Australian consumer remedies, and a payment brand or local currency display does not create a local regulator for the casino.
This matters to searches for an Australian casino using paysafecard. Even if a site claims to accept that payment method, acceptance alone says nothing about its legal status, oversight, or the protections available to a person in Australia. It is a payment detail, not a regulatory credential.
The distinction is material: the law places the prohibition on operators providing the service, while it does not explicitly criminalise the player’s use of an offshore site. That does not remove the consumer risk. A transaction can be completed without the service being lawful to offer in Australia or covered by Australian consumer protection.
Payment method and legal status are separate questions. A payment option cannot make an otherwise prohibited online casino service lawful in Australia. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people physically located in the country. This applies to casino-style games whether a service describes payment as a paysafecard transaction, a card payment or another route.
The practical meaning of “paying with paysafecard” would depend on a service actually offering that method and on its transaction terms. The payment label does not establish those terms. It does not, by itself, specify how a payment is initiated, whether a transaction will be accepted, or whether the method can be used for any other purpose. Those are distinct points, not interchangeable descriptions of one feature.
Australian payment habits include contactless cards, mobile wallets and services linked to bank accounts, including PayPal. That context does not establish paysafecard availability or place it on the same footing as those methods. Nor does a general description of a payment method establish that a particular operator accepts it for Australian customers.
A separate financial check concerns verification. Online casinos typically require customers to complete a Know Your Customer assessment before financial transactions. That requirement is independent of the payment label and does not confirm that any particular method is available.
For a comparison of payment options, the useful distinction is between a method being mentioned and the transaction conditions being specified. A complete set of conditions would identify the relevant service, the permitted transaction type and the applicable terms. Without those details, a claim about paying by paysafecard cannot be treated as a confirmed description of an Australian casino payment route.
This distinction also prevents a payment feature from being mistaken for a recommendation. Describing how a transaction might be labelled does not establish that an operator is lawful, accessible or suitable for Australian residents. The legal position turns on the service being offered, not on the payment instrument attached to it.
Amex deposit and withdrawal limits are set by each casino and can vary. Check the limits shown in the casino’s cashier before making a transaction.
Jackpot City Casino, Spin Palace, Ruby Fortune, Ignition Casino, Joe Fortune and PlayAmo are listed as accepting Amex deposits for Australian players. Acceptance does not mean an operator is authorised to offer online casino games in Australia.
Check whether American Express appears as a payment option in the casino’s cashier. A deposit may still be declined if Amex blocks payments to that website.
Some casinos allow Amex withdrawals, but others do not; you generally need to have deposited with Amex first. Withdrawals can take up to five days to clear, and a fee may apply.
Yes, Amex casino deposits are processed instantly. Withdrawals can take up to five days to clear.
Yes, some online casinos accept American Express deposits, but not all do, and some may not allow withdrawals to Amex. Visa may be accepted more widely at Australian online casinos.
Prepared by the SpinsUP Casino editorial staff.