Google Pay availability depends on the operator and transaction, while deposit and withdrawal routes and conditions may differ.
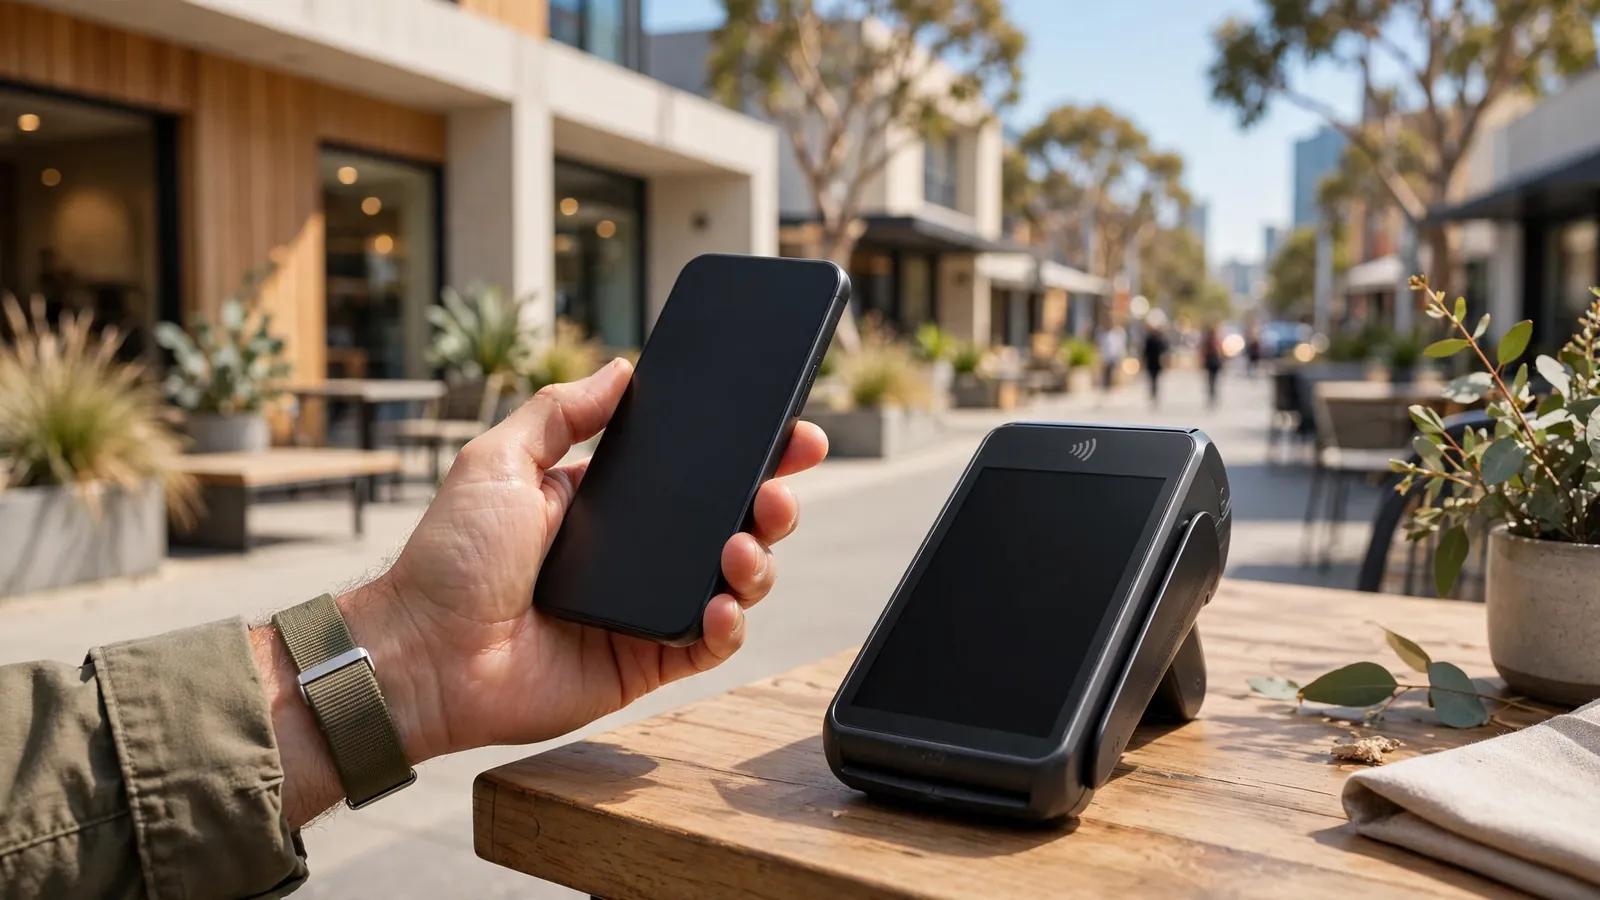
Contactless card payments are part of everyday commerce in Australia. Credit and debit cards are accepted almost everywhere, and mobile wallets, including Google Pay and Apple Pay, are also widely accepted. That broad familiarity explains why a digital wallet can seem like a natural option for an online payment. It does not establish that a particular casino cashier offers Google Pay.
The distinction is between general payment habits and a specific merchant’s available payment methods. A method’s presence across Australian shops and services says something about its familiarity in the wider market. It says nothing conclusive about whether an individual online cashier lists it, permits it for a particular transaction, or makes it available to customers in Australia. Acceptance in one setting cannot be carried over as proof of acceptance in another.
This matters because “Google Pay is widely accepted in Australia” and “this casino accepts Google Pay” are different statements. The first concerns a broad pattern across merchants. The second is a claim about a named operator and its own payment arrangements. The broad statement cannot substantiate the specific one by itself, however familiar the wallet may be.
Google Pay availability can vary by casino and payment method, so check the cashier before making a deposit. This list offers a concise reference for readers exploring casino options in Australia for 2026.
Bizzo Casino
Bizzo Casino is listed with a license from the Curacao Gaming Control Board, held by TechSolutions Group N.V.
Vegaz Casino
Vegaz Casino is licensed under Curacao OGL/2024/1335/0780. Its minimum deposit is EUR 20.
Neospin
Neospin is licensed by the Curacao Gaming Control Board under OGL/2023/176/0095, with Hollycorn N.V. identified as the license holder.
Ricky Casino
Ricky Casino lists a minimum deposit of A$20, or A$30 to qualify for the bonus. Its stated payout times are under an hour for crypto and 1–3 business days for PayID.
7Bit Casino
7Bit Casino is licensed in Curacao and operated by Dama N.V.
Kingmaker
Kingmaker lists a minimum deposit of A$30. Its stated payout times are around 90 minutes for crypto and 1–5 days for fiat.
WinSpirit Casino
WinSpirit Casino is licensed under Curacao eGaming OGL/2024/923/0383, with Antillephone N.V. identified as the license holder. Its minimum deposit is A$30.
Playfina Casino
Playfina Casino is associated with Curacao eGaming and Hollycorn N.V. and has been since 2017. Its minimum deposit is A$20–30, depending on the offer.
Golden Pokies
Golden Pokies is listed as licensed in Curacao.
DragonSlots Casino
DragonSlots Casino is licensed by the Curacao Gaming Authority, with Jumpman Gaming Ltd identified as the license holder.
Australian consumers are comfortable moving between cards, mobile wallets and services linked to banks, such as PayPal. That flexibility is a feature of payment habits, not a guarantee that every business supports every option. A cashier has its own list of available methods; it cannot be inferred from what is common elsewhere.
The same distinction applies to an online service described as mobile-friendly. A mobile interface and a mobile-wallet payment option are not interchangeable claims. The first concerns how a service is accessed or displayed; the second concerns whether a payment method is offered. A reference to Google Pay in general promotional or descriptive language is not, on its own, confirmation of a Google Pay option in the cashier.
Nor does the presence of a wallet on a phone settle the matter. Payment availability is determined by the merchant’s arrangements, rather than by the fact that consumers can use the wallet in many other places. The relevant evidence would be an explicit, current cashier listing that applies to the particular service and the relevant transaction. Without that, broad Australian acceptance remains background context, not proof.
The difference can be seen without treating all payments as equivalent. A contactless card may be accepted at a physical point of sale; a mobile wallet may be familiar across Australian businesses; a bank-linked service may be another established option. Each fact describes a method in a broad setting. None establishes the payment choices presented by a separate online cashier.
Even when the same payment brand appears across different services, its presence in one place does not demonstrate its availability elsewhere. Merchants make their own decisions about the methods they present. As a result, a general statement about Australian payment culture cannot identify which options a particular cashier supports.
This is also why broad labels can create a misleading impression. “Australian online casino” may describe the audience a page is discussing, but it does not itself confirm a method’s availability to that audience. Likewise, calling a service a mobile casino does not verify that Google Pay appears among its payment choices. The method has to be tied to the actual cashier, rather than inferred from the country, the device or the category of service.
A precise claim therefore needs a precise basis. It should identify the operator and make clear that Google Pay is currently shown as an available method for the relevant transaction. General statements about widespread mobile-wallet use do not supply those details. They can explain why the question is plausible, but they do not answer it.
There is no contradiction between widespread wallet use in Australia and uncertainty about an individual cashier. One concerns how broadly consumers encounter mobile wallets; the other concerns a specific merchant’s payment options. Treating these as separate questions avoids turning a general market observation into an unsupported assurance.
The same care applies to claims that a method is accepted by an entire category of services. A category-wide claim implies that acceptance has been established across the services covered by it. A general fact about contactless cards or mobile wallets cannot support that implication. If the available information concerns only Australian payment habits, the accurate conclusion is limited to those habits.
Google Pay’s familiarity may make it recognisable as a payment option, but recognition is not confirmation. The distinction is practical: a payment method can be common in daily commerce while remaining unconfirmed for a particular online cashier. A claim about a specific casino must rest on that cashier’s own stated options, not on the wider popularity of mobile wallets.
A claim that a casino accepts Google Pay is useful only when it refers to the particular transaction in question. Recognition of the wallet’s name, or the presence of a Google Pay logo on a general payments page, does not establish that an Australian customer can use it to fund a gambling account. The relevant evidence is narrower: whether Google Pay appears as an available option in that operator’s cashier for the account, location and transaction being described.
That distinction matters because payment acceptance is not a single, universal status. A method can be supported in one context and unavailable in another. A page may describe a wallet in general terms without showing whether it can be selected for a casino deposit. A logo may indicate a broad technical association, not a completed payment route. Neither item alone confirms that a deposit will be accepted.
A specific deposit claim needs to connect the method to the transaction. The strongest indication would be Google Pay displayed in the cashier as a selectable deposit method, followed by terms that identify any conditions attached to that option. The display should relate to the relevant account and jurisdiction, rather than an undifferentiated list of payment brands.
Even that evidence has limits. A cashier option indicates that a route is presented; it does not by itself prove that every attempted payment will be approved. The transaction may also depend on account status, payment-provider checks and the rules applied by the financial institution or wallet. A claim that a method is available therefore should not be inflated into a promise that a payment will succeed.
Account verification is another separate condition. Online casinos commonly conduct Know Your Customer checks before allowing financial transactions. In practice, this means that a deposit option and permission to transact are not necessarily the same thing: account checks may affect whether financial activity can proceed. A statement about Google Pay acceptance that omits such conditions can leave the impression of unconditional access when the method’s presence in a cashier does not establish that.
The phrase “a Google Pay deposit” does not establish a minimum or maximum amount. It also does not settle whether a fee applies, whether the transaction is processed in Australian dollars, or whether limits differ by account or payment route. Those are distinct terms and require their own evidence. A method name cannot be used as a substitute for a published transaction condition.
For the same reason, a specific low-deposit figure cannot be inferred merely from the fact that a wallet is widely recognised. A statement that a casino accepts Google Pay at a particular amount would need to be supported by the relevant cashier terms or a clear transaction record. Without that, attaching a figure to the method turns a general payment reference into a financial claim with no demonstrated basis.
Fees require the same care. A wallet transaction might involve conditions imposed by the casino, payment provider, card issuer or bank. A general mention of Google Pay does not identify which party, if any, charges a fee. Nor does it establish that a displayed amount is the final amount debited. Any fee statement should identify the applicable condition rather than treating the wallet itself as proof of a cost-free deposit.
Limits are similarly operator- and transaction-specific. A general payment page cannot establish the permitted deposit range for a particular account. A reliable description would need to show the limit that applies to the relevant route and explain whether it is a casino condition or a restriction imposed elsewhere. Without that distinction, a number can be accurate in one setting and misleading in another.
There is also a difference between a deposit route being listed and a deposit being completed. A cashier may present a payment choice, while the final transaction remains subject to approval and account checks. A successful deposit record would establish that a particular transaction went through; it would not automatically establish a universal rule for other customers or later transactions.
This is why descriptions such as “Google Pay is accepted” need a defined scope. The statement may refer to a logo, a listed option, or a successful payment. These are not interchangeable levels of evidence. The more consequential the claim—especially when it names a deposit amount, fee or limit—the more precisely it must identify what was observed and under what conditions.
A sound deposit description should therefore separate four points: whether Google Pay is shown in the cashier, what account and location the information applies to, what conditions govern the transaction, and whether the claim concerns an available option or a completed payment. Without those distinctions, familiarity with the wallet can be mistaken for proof of a working casino deposit route.
A ranking of Australian casino sites accepting Google Pay would require comparable, operator-specific evidence that the payment method is available to Australian customers. Familiarity with a wallet, or a general statement that a site supports digital payments, does not establish that Google Pay appears in its cashier or can be used for a particular transaction. Without that distinction, a “best” list would rank assumptions rather than confirmed acceptance.
The relevant comparison is not simply whether a brand mentions Google Pay somewhere. Availability may depend on the customer’s location, account status, transaction type and the payment options displayed by the operator. A site might support a method for some customers without offering it to Australian residents. A payment logo or broad label such as “mobile payments” would not settle those details. A comparison that treats these signals as equivalent would give the appearance of precision without a consistent basis.
Evidence about other payment methods cannot fill that gap. A specialist review has reported that some online casinos do not accept American Express, while another specialist review has suggested Visa may be more widely accepted than American Express at Australian online casinos. Those observations concern card acceptance, not Google Pay. They also do not support conclusions about every operator: payment arrangements can differ between sites and may change. Transferring a card comparison to a mobile wallet would be a category error, not a useful shortcut.
The same limit applies to operator names. A site’s reported support for Amex, Visa or another payment service is not proof that Google Pay is available. Nor does naming a casino alongside a wallet make the connection reliable unless acceptance is confirmed for the relevant customer and transaction. No responsible ranking can be built by substituting one payment method for another or by repeating a brand association without evidence tied to the cashier.
A meaningful comparison would need to establish the same points for each operator: whether Google Pay is explicitly offered to Australian customers, whether the option applies to deposits, and whether the terms shown by the operator match the transaction being compared. The evidence would also need to be current and consistent across the sites under review. Otherwise, one entry might be based on an operator’s own cashier while another rests on a third-party description, leaving the ranking with unlike inputs.
This matters particularly when a list uses labels such as “best” or “instant.” “Best” requires a defined basis for comparison; it cannot be inferred from a payment logo. “Instant” would require transaction-specific timing evidence and cannot be borrowed from a different method or from a statement about deposits when the comparison concerns withdrawals. Those are separate claims and need separate support.
Accordingly, no named-site comparison of Google Pay acceptance can be justified here. That is not a judgment that a particular operator does or does not offer the wallet. It is a boundary on what a ranking can establish: without comparable confirmation of Google Pay itself, there is no sound basis for placing one site above another or recommending a supposed best option.
The distinction is straightforward. Evidence that some casinos accept a particular card can support a limited statement about that card; it cannot establish a Google Pay shortlist. A comparison becomes informative only when each entry is supported by equivalent, transaction-specific confirmation. Until then, a ranked list would present an unverified payment claim as a consumer recommendation, and the ranking would add no reliable information.
A payment arriving quickly and a withdrawal reaching an account are different transactions. A deposit moves funds into an operator’s account; a withdrawal moves funds out, often through a separately defined process. The speed of one direction cannot be used to calculate the other.
That distinction matters when a cashier displays Google Pay as a deposit option. A successful payment would show that the inbound transaction was accepted. It would not, by itself, establish that Google Pay is available for payouts, that the same account can receive them, or how long a withdrawal would take. A deposit receipt is evidence of a deposit, not a timetable for money leaving the casino.
Payment terms may illustrate the difference. A specialist review reports that Amex deposits at casinos are processed instantly, while Amex withdrawals may take as long as five days to clear. Those figures concern Amex and should not be transferred to Google Pay. Even for the same method, the deposit and withdrawal routes can have separate processing times; the deposit speed is not a promise about the withdrawal.
A casino may also distinguish between submitting a withdrawal request and the funds clearing through a payment provider. These are separate stages, so a time attached to one stage should not automatically be read as the total time until funds are available. The relevant terms are those that specify the payment method, the direction of the transaction and what the stated timing measures.
For Google Pay, a claim of instant deposits would therefore say nothing about instant withdrawals. Nor would a fast deposit establish that a payout can be sent back to Google Pay at all. The method shown for adding funds and the method offered for receiving funds are not necessarily identical. The cashier’s withdrawal options and the operator’s applicable terms determine the route, rather than the name displayed beside a deposit button.
Searches for fast Google Pay withdrawals often combine several separate expectations: that Google Pay can be used, that it is accepted for withdrawals, and that the payout clears promptly. Each needs its own transaction-specific support. A claim about deposits can substantiate only the inbound side. It cannot establish an outbound route or its timing.
The practical comparison is narrow but important: speed is not a property that automatically carries over from one direction to the other. For any payment method, the deposit stage and withdrawal stage need to be assessed separately. An instant deposit label, where one is stated, is not a withdrawal estimate. A withdrawal estimate, in turn, needs to identify the relevant route and stage before it can be compared with another method.
This is why “instant” should be treated as a description of a particular transaction, not a general service promise. Without a stated Google Pay withdrawal route and a timing attached to that route, deposit speed cannot supply either one. The calculation stops at the boundary between money going in and money coming out.
A payment option does not determine whether an online casino may legally serve people in Australia. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino services to people physically located in the country. That prohibition applies regardless of whether a site promotes Google Pay, accepts a bank-linked payment service or processes transactions through another route.
The legal distinction is between the operator’s conduct and the individual player’s position. The Act does not explicitly make it a criminal offence for a person in Australia to use an offshore casino. That does not make the service lawful for the operator to provide, nor does it create an Australian consumer-protection framework for the transaction.
The Australian Communications and Media Authority (ACMA) administers enforcement of the Act. Offshore operators are not made compliant with Australian law merely by accepting Australian currency or offering a payment method familiar to local customers. A cashier option describes a transaction route; it is not evidence of local authorisation. In this market, the legal issue is the provision of the casino service itself, not the branding of the wallet used to fund it.
Australian consumer law does not protect players using offshore casinos. If an operator delays or refuses a payment, closes an account or disputes a balance, the customer cannot assume that Australian consumer protections provide a remedy against that offshore service. The practical difference is material: a familiar interface and an Australian-facing page do not establish local accountability.
The law is also enforced in practice. Offshore casino services are subject to blocking measures, so apparent online availability is not a reliable indicator that a site is legally permitted to operate in Australia or will remain accessible. A site’s payment page can change independently of its legal position; neither a listed wallet nor a successful transaction settles that question.
The same boundary applies to searches for casinos that accept Google Pay in Australia. Such wording describes a desired payment feature, not a legal category or an endorsement. Even if an offshore site claims to accept the wallet, that claim would not override the prohibition on operators providing real-money online casino services to people in Australia. Nor does the absence of explicit criminalisation of players convert the operator’s service into an authorised one.
For that reason, statements about a casino “serving Australian residents” need to be read carefully. A site may be accessible, use Australian terminology or display a payment option, while the underlying service remains prohibited under the Act. Accessibility is a technical condition; legality is a separate question. The distinction is less convenient than a payment badge, but it is the one that determines the legal position.
The relevant calculation is therefore not whether a wallet appears in a cashier, but whether the service is legally available to people in Australia and what protection exists if a dispute arises. For offshore casino use, Australian consumer law does not supply that protection.
A payment label and a game catalogue describe different things. A cashier may list a payment method without establishing which services an operator offers, while a game page cannot confirm that a particular payment route is available. Treating “Google Pay casino games” as one combined feature collapses two separate checks into a claim that neither detail proves on its own.
This distinction matters in Australia because payment information does not determine whether an online casino service may lawfully be offered. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia. A Google Pay logo, a deposit option, or a reference to mobile casino access does not alter that restriction.
Nor does the presence of a game category establish that it is accessible to Australian residents through a lawful service. A description of casino games using Google Pay could refer only to a payment method, only to games, or to an unsupported combination of the two. Without transaction-specific evidence, it should not be read as confirmation that Google Pay funds play or that any particular game is available.
The same separation applies to mobile services. A site being designed for phones does not mean Google Pay is accepted, and mobile-wallet acceptance would not establish the legal status of casino games offered through that site. These are independent properties, not interchangeable assurances.
The practical distinction is straightforward: payment-method claims concern how a transaction is proposed to be made; game claims concern what an operator provides. Neither should be used as evidence for the other. In Australia, the legal restriction on operators offering real-money online casino games remains relevant regardless of the payment method named. A payment reference therefore cannot turn a prohibited service into a permitted one, and a game description cannot verify a Google Pay transaction.
This is why casino payment wording should be read narrowly. It may describe a cashier option, but it does not, by itself, substantiate the availability, access conditions, or legal status of any casino game.
A phrase linking Google Pay with casino slots combines separate claims: that a gambling service offers a particular category of game and that its cashier accepts a particular payment method. Neither claim proves the other. A page using that wording may reflect a search label or promotional framing, not a confirmed payment option for a transaction.
Google Pay and Apple Pay are widely accepted across Australia in everyday commerce. That broad availability concerns ordinary retail payments; it does not establish that an online casino cashier supports Google Pay, or that the method can be used for a gambling transaction. The word “slots” adds no payment evidence. It identifies a subject, not a cashier setting or an accepted route.
The same distinction applies to wording about a Google Pay casino bonus. A bonus label does not show that Google Pay is accepted, that a deposit made with it qualifies, or that any offer’s conditions are satisfied. Treating promotional language as proof of payment compatibility would collapse several separate terms into one unsupported conclusion.
A meaningful payment claim would need to specify the operator and transaction: whether Google Pay appears as an available method in that operator’s cashier, and whether it applies to the relevant deposit or withdrawal. A general reference to games, bonuses or a list of casinos does not supply those details. Nor does the presence of Google Pay as a familiar mobile wallet establish that a gambling service can accept it.
The distinction is especially important when a page presents game-related wording beside payment logos or promotional text. Those elements can create an impression of connection without confirming that the method is available for the transaction in question. The useful evidence is the cashier’s stated payment terms, not an association between a game category and a wallet name.
Accordingly, “Google Pay slots” wording should be read as a description of a topic, not confirmation of a working payment route. Game-related labels, bonus language and wallet acceptance are separate matters. Only a transaction-specific statement from the operator can establish whether Google Pay is offered for a particular payment, and the label alone cannot do that.
A payment option displayed for deposits does not, by itself, establish that the same route is available for a withdrawal. The cashier can apply separate rules to money going into an account and winnings being paid out. That distinction matters when assessing claims about Google Pay: a deposit route cannot be treated as evidence of a Google Pay withdrawal route.
American Express provides a concrete illustration. A specialist review describes casino rules under which a withdrawal to Amex is available only after the account holder has previously deposited using Amex. In that case, the deposit history is a condition of the payout route, not proof that every casino supports it. The same review notes that some casinos may decline Amex withdrawals or apply an additional fee. These are reported operator-specific conditions, not a universal rule for Australian casinos.
Another specialist review states that Amex withdrawals are not available at every Australian online casino. The practical point is narrow: even where a payment method appears at the deposit stage, its treatment at cash-out can differ. Any assessment of an online casino with Google Pay withdrawal therefore needs transaction-specific confirmation of the withdrawal method, its eligibility conditions and any applicable charge. A Google Pay logo or deposit option alone does not settle those terms.
A specialist review notes that Amex withdrawals may only be available after a previous Amex deposit, and some casinos may decline these withdrawals or apply additional fees.
The route can also depend on the casino’s own payment rules. Amex withdrawal eligibility, for instance, may hinge on a previous Amex deposit; that condition should not be transferred to Google Pay without evidence. Nor should Amex’s restrictions be read as evidence that Google Pay is either accepted or refused for withdrawals. They show only that deposit and payout arrangements can be method-specific.
For a casino withdrawal using Google Pay, the relevant distinction is whether the cashier explicitly offers Google Pay for withdrawals, not merely whether it lists Google Pay for deposits. The method name appearing in one transaction direction is insufficient to establish availability in the other. Withdrawal conditions should be read separately from deposit terms, including any requirements tied to the original funding method. A clear route requires a stated payout option and its conditions; resemblance between two payment methods is not a condition.
Australians are accustomed to moving between card payments, mobile wallets and services connected to bank accounts, including PayPal. That familiarity describes consumer behaviour across ordinary transactions; it does not establish which options a particular casino makes available in its cashier. A payment method can be familiar in Australia and still be absent from a specific operator’s payment menu.
The distinction matters when assessing whether an Australian casino accepts Google Pay. National comfort with mobile wallets is not evidence that a particular gambling operator supports Google Pay for deposits, or that it allows the same route for withdrawals. Acceptance is an operator-level condition, not a general feature that can be inferred from how people pay elsewhere.
Card acceptance also varies by method. A specialist review reports that Visa may be accepted at more Australian online casinos than Amex. That is a comparison attributed to the review, not a fixed rule for every operator or a current guarantee. It illustrates why a broad label such as “card payments accepted” leaves important detail unresolved: the cashier may distinguish between card networks, and availability can differ between casinos.
The same caution applies to mobile wallets. A casino using Google Pay would need to show that option in its own current cashier and specify which transaction types it supports. General acceptance of Google Pay by Australian merchants does not answer either point. Nor does the presence of bank-linked services imply that a wallet is available as a separate payment route.
For a useful comparison, the relevant unit is the individual cashier and its stated terms. Payment preferences across Australia can explain why cards and wallets are familiar; they cannot substitute for operator-specific acceptance information. A claim that an Australian casino takes Google Pay therefore requires evidence tied to that casino, rather than an assumption based on the country’s wider payment habits.
A claim that a casino accepts Google Pay needs to identify the transaction it covers. General acceptance of mobile wallets across Australia does not show that a particular gambling cashier offers Google Pay, or that the option remains available when a payment is submitted. The payment route is determined by the operator’s actual terms and transaction process, not by how widely the wallet is used elsewhere.
Deposit and payout claims also require separate support. A Google Pay option for adding funds would not, by itself, establish that winnings can be returned through the same service. Nor does a general reference to a “Google Pay casino” settle whether the wallet is available for a specific account or payment. Each statement should be read narrowly: which transaction, under which conditions, and according to what current operator information?
Account checks matter to the transaction as well. Online casinos commonly require identity verification before allowing financial activity. That process is distinct from wallet acceptance: completing a Know Your Customer assessment does not prove that Google Pay is supported, and a wallet option does not remove verification requirements.
The useful standard is therefore precise evidence tied to the relevant payment direction. A broad statement that Google Pay is accepted in Australia cannot establish that it can be used at a casino, whether for a deposit or a payout. Without transaction-specific terms, acceptance should not be treated as confirmed. The distinction is not technical fine print; it determines whether the payment route described is actually available for the stated purpose.
Limits are set by each casino and can vary. Check the operator’s cashier for its current Amex deposit and withdrawal limits.
Amex deposits are typically free, but a casino may charge a 1.5% surcharge, and Amex cards incur a 3% currency conversion fee. Withdrawal fees may also apply.
Yes, at casinos that accept American Express, gift cards can be used for deposits only.
Some casinos do not allow withdrawals to Amex, and you generally need to have deposited with Amex first. Where available, withdrawals can take up to five days to clear and may incur a fee.
Amex deposits typically have no fees, but a casino may apply a 1.5% surcharge. A 3% currency conversion fee may also apply to Amex cards.
Jackpot City Casino, Spin Palace, Ruby Fortune, Ignition Casino, Joe Fortune, and PlayAmo are listed as operators that accept Amex deposits for Australian players.
Created by the ”SpinsUP Casino” editorial team.