PayID, POLi and bank wires differ in how deposits, withdrawals, verification and timing are handled, while Australian law restricts real-money online casinos.
“Bank transfer” can describe several different ways of moving money, not one payment method with a single set of rules. In discussions of online pokies, the label may refer to PayID, POLi, or a conventional bank wire. Card payments are a separate route, even when they draw on the same bank account. The distinction matters because a method available for adding funds does not necessarily provide a way to receive a withdrawal.
There is also a legal limit to this discussion in Australia. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including pokies, to people located in Australia. Payment labels do not change the status of the service. The descriptions below explain how the methods differ; they are not an endorsement or invitation to use an online casino.
PayID is used through a participating bank’s payment service. Rather than entering conventional account details, a sender can use an identifier such as a mobile number or email address. In a casino-payment context, it is generally presented as a way to send a deposit from a banking app.
Choosing an instant bank transfer casino in Australia means checking the payment details that are actually available, rather than assuming every site offers the same transfer options or speeds. Use these operator notes as a starting point and verify the payment methods and terms that apply to you.
Bizzo Casino
Bizzo Casino is listed with a Curaçao Gaming Control Board licence held by TechSolutions Group N.V.
Vegaz Casino
Vegaz Casino holds licence OGL/2024/1335/0780 in Curaçao. Its stated minimum deposit is EUR 20.
Neospin
Neospin is listed under Curaçao Gaming Control Board licence OGL/2023/176/0095, held by Hollycorn N.V.
Ricky Casino
Ricky Casino lists PayID payouts at 1–3 business days and crypto payouts under 1 hour. The minimum deposit is A$20, or A$30 to qualify for the bonus.
7Bit Casino
7Bit Casino is listed as Curaçao-licensed and operated by Dama N.V.
Kingmaker
Kingmaker lists crypto payouts at about 90 minutes and fiat payouts at 1–5 days. Its minimum deposit is A$30.
WinSpirit Casino
WinSpirit Casino holds Curaçao eGaming licence OGL/2024/923/0383, issued to Antillephone N.V. Its stated minimum deposit is A$30.
Playfina Casino
Playfina Casino is listed as Curaçao eGaming-licensed, with Hollycorn N.V. since 2017. Its minimum deposit is A$20–30, depending on the offer.
Golden Pokies
Golden Pokies is listed with a Curaçao licence.
DragonSlots Casino
DragonSlots Casino is listed under the Curaçao Gaming Authority, with Jumpman Gaming Ltd as operator.
That makes PayID different from paying by card: the payment is initiated through the bank, rather than entered as a card transaction. It is also distinct from a conventional bank wire, which relies on bank-account details and may involve a more formal transfer process. The name “bank transfer” is sometimes used broadly for all of these, but treating them as interchangeable can obscure the actual route and its conditions.
PayID’s role in a deposit should not be taken as evidence that the same route is available for withdrawals. The payment method shown for sending funds and the options offered for receiving them are separate matters. A site’s displayed payment logos or a general claim that it accepts bank transfers do not, by themselves, establish that withdrawals can be made through every listed method.
POLi is another bank-linked payment option that may appear among deposit methods. Its function should be understood narrowly: POLi is mainly used to fund an account, and it should not be assumed to support cash-outs. A deposit option is not a complete description of the account’s payment arrangements.
This distinction is particularly relevant when “bank transfer pokies” is used as a loose label. A POLi payment and a PayID payment may both involve a bank, but they are not the same service. Nor does the presence of POLi indicate that a conventional bank transfer is supported. Each route has to be identified by its actual name and purpose.
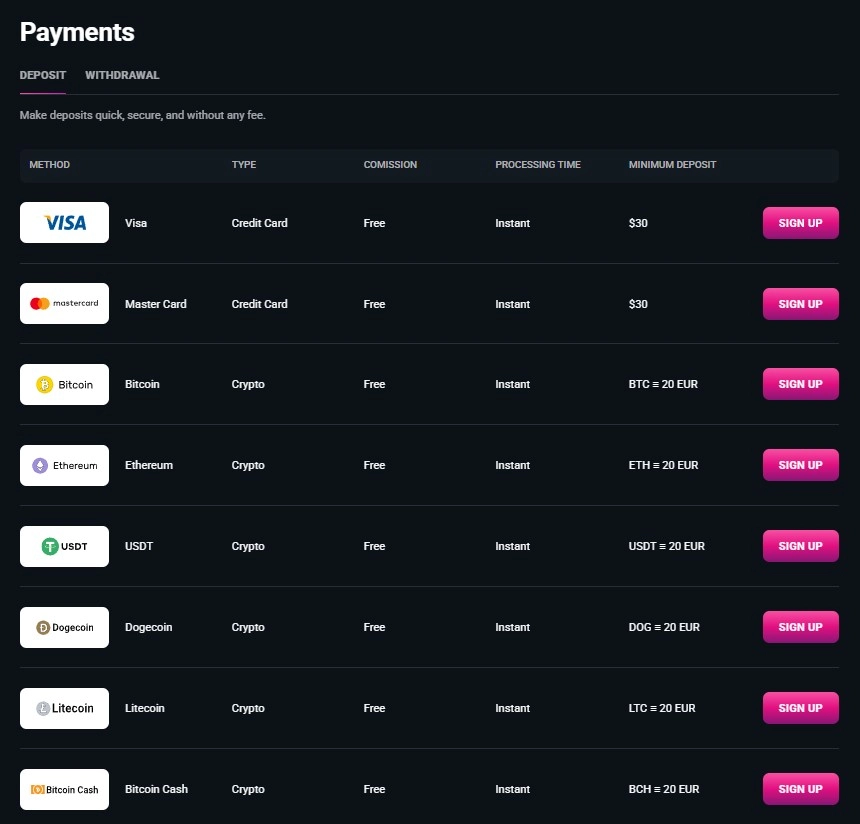
Visa and Mastercard are commonly listed for deposits. A specialist review reports that card withdrawals may be slower than deposits or may not be available, depending on the processor. That qualification is important: card acceptance for incoming payments does not establish that a card can be used to receive funds. The card network, payment processor and operator’s available withdrawal routes all affect what is possible.
A card transaction can be connected to a bank account, but that does not make it a bank transfer. This is more than terminology. A page that groups cards, PayID, POLi and bank wires under one “bank transfer” heading can make the payment choices appear more uniform than they are. The deposit and withdrawal sides may differ, and the method used to pay may not be the method available for a payout.
For an Australian reader, “online casino bank transfer” may refer to several distinct arrangements. PayID is a bank-based payment route; POLi is mainly a deposit option; a conventional wire uses bank-account details; and Visa or Mastercard payments are card transactions. These categories should not be collapsed simply because each may involve a financial institution.
The practical distinction is between a method that is listed for depositing and a method confirmed for withdrawals. A general “bank transfer accepted” label says little about which transfer service is meant or whether it works in both directions. Payment names should therefore be read as specific routes, not as interchangeable descriptions of moving money.
This terminology also avoids implying that every online casino available in a search result is lawful for Australian customers. Under Australian law, real-money casino-style services—including pokies and other casino games—cannot be provided to people physically in Australia. The payment method does not create an exception to that restriction.
PayID is an identifier-based payment service that operates through Australia’s New Payments Platform (NPP). Instead of relying on a BSB and account number as the visible destination details, a payment can be addressed using an identifier such as a mobile number or email address. The identifier connects the payment to an account; it is not itself a separate bank account or a casino payment system.
The NPP is the payment infrastructure behind the transfer. PayID payments settle through that network in real time, which is why the banking leg can be near-instant rather than waiting for a conventional bank transfer to be processed in batches. A successful settlement means the funds have moved between accounts. It does not establish that a particular merchant or service is lawful, or that an account elsewhere has been credited.
That distinction matters when the phrase “instant bank transfer” is used for an online casino payment. It describes the potential speed of the PayID rail, not the complete journey from payment initiation to a balance being shown on a third-party account. The bank network and the receiving service perform different functions. A real-time settlement at the first stage cannot determine what happens at the second.
PayID is part of Australia’s banking payment infrastructure, rather than a card network or an e-wallet. Its identifier makes the destination easier to address, while the NPP carries and settles the payment. The service can be used to send and receive money between participating accounts, but the presence of PayID on a payment page does not change the nature or legal status of the business receiving funds.
For Australian readers, the legal boundary is material. Under the Interactive Gambling Act 2001, operators are prohibited from providing real-money online casino games, including pokies, to people physically located in Australia. A payment method’s availability does not make such a service lawful. PayID is a general payment service; it is not an endorsement, authorisation or safeguard for every business that may claim to accept it.
The word “instant” should therefore be read narrowly. It refers to real-time settlement through the NPP, not a promise about account crediting, service access or any later transaction. The payment rail can complete its part quickly while the receiving organisation applies its own processes. Those are separate clocks, and treating them as one creates a misleading picture of speed.
PayID’s useful technical feature is straightforward: a familiar identifier can direct a payment, and the NPP can settle it in real time. For any payment, the recipient and purpose remain separate questions from the network’s capability. In the context of online pokies, the legal restriction on operators remains decisive; a fast transfer cannot alter it.
A payment screen can make a deposit look like a routine bank transaction. The legal position in Australia is not routine: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including pokies, to people physically in the country. The steps below describe the payment details that may appear in a PayID request; they are not a recommendation to fund an online casino account.
PayID Deposit Process
Method Selection
Select PayID as the payment method on the deposit screen.
Amount Entry
Enter the desired deposit amount into the field.
App Confirmation
Open your banking app and confirm the payment request.
A PayID payment is initiated through a banking app. In a casino deposit flow, the stated sequence is to select PayID, enter an amount and confirm the payment in the app. That sequence does not itself establish that the recipient is entitled to provide casino services in Australia. A payment request should not be treated as proof of legality or as a reason to proceed.
The minimum shown on a deposit page is an operator-set condition, not a standard feature of PayID. Casino deposit offers commonly begin at AUD 10–20, while some bank-transfer deposit pages accept AUD 5. These figures describe reported entry points, not a market-wide rule; the amount displayed for a particular payment request may differ.
The amount entered into a payment screen should match the amount requested by the recipient. A mismatch can make a transaction harder to identify, particularly if a deposit relies on a reference to connect the transfer with an account. The banking app should show the intended amount and recipient before confirmation. If either differs from the details presented for the payment, the transfer should not be confirmed.
The word “instant” concerns the movement of a payment, not the status of an account balance. A transfer may reach a recipient while an associated deposit remains uncredited because the operator cannot match it to the account. Payment confirmation and account credit are separate events.
A payment reference can connect a transfer to the player account. Some casino payment instructions require the player ID or username in that field so the payment can be credited automatically. If the identifying detail is omitted or entered incorrectly, the deposit may remain pending and require manual processing by support.
The reference should be copied exactly as displayed in the payment instructions, including any required player ID or username. A unique reference in the payment description helps distinguish one transfer from another; an altered, incomplete or reused reference can create an avoidable reconciliation problem. The reference is not a substitute for checking the recipient name, and it does not change the legal status of the service.
Before any confirmation screen is accepted, the recipient name should be checked against the payment details supplied. A mismatch is not a minor formatting issue: money sent to an unintended recipient may not be credited to an account. The final check should cover the recipient, amount and reference together, rather than treating the banking app’s confirmation as proof that all three are correct.
The banking app’s confirmation records the player’s instruction to send funds. It does not prove that an account balance has been updated. Where a payment has been sent but not matched, the reference is the first detail to compare with the instructions. A pending status may require support processing, but it should not be assumed that a second payment will resolve the problem; duplicate transfers can create a separate reconciliation issue.
For Australian residents, the central decision comes before the payment sequence: real-money online casino services are prohibited from being offered to people in Australia. A polished deposit page, low minimum or rapid payment confirmation does not alter that restriction. The practical distinction is simple: a bank app can confirm that funds were sent, while neither that confirmation nor a displayed balance makes the underlying casino service lawful.
A bank transfer option is a payment feature, not evidence that an online casino may legally offer real-money games in Australia. Under the Interactive Gambling Act 2001, operators are prohibited from providing online casino-style games, including pokies, to people physically in Australia. A foreign licence does not change that position. The presence of a deposit page, Australian-dollar figures or a local payment option is not a substitute for legal authority.
That distinction matters when assessing claims about the best casino sites that accept bank transfers. A polished payment flow can establish only that the site says it accepts a transfer. It cannot establish that the service is lawful, that a deposit will be credited correctly or that a withdrawal will be paid. Treating payment access as a quality rating confuses an operational detail with the larger risk.
Before any transfer is considered, the recipient name displayed by the banking app should match the payment instructions supplied by the site. A mismatch, an unexplained third-party recipient or a last-minute change to the account details is a reason not to proceed. The destination name is a basic control: once a payment is sent, recovering it may not be straightforward.
Payment instructions should also specify whether a reference is required and what information it must contain. Where the site requires a player ID or username, leaving it out can prevent automatic crediting and leave the payment pending for manual handling. A unique reference and a careful check of the code reduce avoidable reconciliation problems; they do not make the underlying service lawful or guarantee a refund.
Claims about a mobile casino accepting instant bank transfer require the same scrutiny. A transfer initiated through a banking app does not prove that the site has received or correctly allocated the funds. The payment route and the operator are separate parts of the transaction, and a smooth interface says little about the operator’s record.
For Australian residents, there is no local licence that authorises an operator to provide real-money online casino games in breach of the Act. A foreign licence should therefore not be presented as Australian approval. Licence statements can still be checked for what they actually claim: the issuing jurisdiction, the named operator and whether the licence details correspond to the site. That check is not an endorsement or a route around Australian law.
Payout claims also need evidence beyond promotional wording. A published policy should explain how requests are handled, what conditions apply and what can delay payment. Independent reporting may add context, but an isolated complaint or a positive testimonial is not a payout record. Look for consistent, specific information and distinguish a reported experience from a binding commitment by the operator. A transfer option alone establishes none of those terms.
A specialist review reports that identity checks are generally required before a first withdrawal. Completing KYC verification early can reduce the chance that paperwork becomes an additional delay when a withdrawal is requested. The documents and submission method should be described clearly, and personal information should be handled through a secure process.
These checks do not resolve the legal issue, nor do they guarantee that funds will be released. They are a separate condition of account processing. If the site’s identity requirements, recipient details or payout terms are unclear or inconsistent, the financial calculation is already incomplete: the advertised deposit route is not enough to establish what happens to the money afterward.
Real-money online casino games, including pokies, are prohibited services when offered to people in Australia under the Interactive Gambling Act 2001. The rules apply to operators providing the service; the payment mechanics below describe what a bank-transfer withdrawal involves, not an endorsement or recommendation to use an offshore casino.
A bank transfer withdrawal requires the account holder’s banking details and documents to verify their identity. The exact fields and documents depend on the operator and bank, so the withdrawal instructions should be checked against the account details before a request is submitted. A mismatch in banking information can delay processing or require the details to be corrected.
KYC verification is a separate part of the process from entering bank details. Identity documents may be needed to confirm that the account and withdrawal belong to the same person. Completing those checks before a withdrawal request can reduce the chance that a request is held while documents are reviewed. It does not remove the operator’s own approval step.
Payment-method rules can also affect the available route. A specialist review reports that some operators may ask for withdrawals to return through the deposit method where that is possible. This is not a universal rule: the operator’s stated terms determine whether a bank transfer can be used after a deposit made by another method. Where the original route cannot accept withdrawals, the operator may specify an alternative.
The time needed to receive funds has two parts: the operator’s review and the bank’s transfer. The payout estimate for a bank transfer should therefore be read as a period after approval, not necessarily from the moment a withdrawal is submitted.
A specialist review describes bank-transfer and card withdrawals as taking one to five business days after approval. The same review puts PayID and some e-wallet or cryptocurrency withdrawals at minutes to hours. These are reported timeframes, not guarantees; an incomplete KYC check, a request for further information or the operator’s processing schedule can change the total wait.
That distinction matters when comparing a casino with bank transfer payout options. A transfer may be initiated only after the operator releases the withdrawal, so the bank’s processing time cannot account for a request still awaiting review. Conversely, an approved request can still take time to appear in the receiving account.
A useful record of the transaction includes the submitted amount, the chosen withdrawal method, the request status and any confirmation from the operator. If the status remains pending, the relevant issue is whether approval is outstanding; if it is marked paid, the bank-transfer period becomes the main timing reference. A casino bank transfer withdrawal should not be treated as instant merely because the deposit method was fast: deposit and payout processing are separate stages.
A PayID payout has two separate clocks: the casino’s review and release process, followed by the payment network’s settlement. PayID payments move through the New Payments Platform (NPP), which can clear a released transfer within minutes. That speed does not start when a withdrawal request is submitted. Until the operator approves and sends the payment, the network has nothing to settle.
The internal review can therefore determine most of the wait. A specialist review of PayID casinos reports that withdrawal requests at its top-rated sites may be accepted within 0–6 hours of submission, with verified accounts typically reviewed and approved within 2–6 hours. Those figures describe the source’s reported operators and conditions, not a service standard across all sites. “Fast” is a processing claim, not a property conferred by the PayID name.
Verification status matters because an account awaiting checks may not be ready for approval. A request can also take longer when the operator needs to resolve a payment or account detail. The practical distinction is between a request being received, a review being completed, and funds being released. Only after release does network settlement time apply.
That distinction matters in Australia’s legal setting. Under the Interactive Gambling Act 2001, providing real-money online casino games, including pokies, to people physically located in Australia is illegal for operators. A payment method’s availability or technical speed does not change that status, and a fast bank transfer label should not be read as evidence that a service is lawful or locally authorised.
For a casino fast bank transfer claim, the useful measure is the time from request to approval, not merely the time PayID takes to clear a released payment. Published timing claims should specify whether they cover operator review, payment release or final receipt. Without that separation, a short network estimate can obscure a longer queue at the casino’s end. The NPP can settle quickly; it cannot approve a withdrawal, complete an account review or make an operator release funds.
A stated review window is also conditional on the account being verified. If that condition is not met, the quoted period may not describe the request at all. Treating the review estimate as a guaranteed arrival time would combine two different processes and overstate what the figure measures. For the same reason, “instant” can refer to network settlement after release, not an instant decision on a pending request.
The relevant comparison is therefore not simply which PayID option claims the shortest transfer time. It is whether a published figure identifies the approval stage and the conditions attached to it. Network speed can reduce the final leg; it cannot erase operator processing time, and it does not establish that an online casino service may legally be offered in Australia.
A bonus linked to a bank-transfer deposit is not extra cash with no strings attached. Its value depends on the conditions attached to it and whether those conditions can be met. The payment method does not make the offer more favourable: paying by bank transfer changes how money is sent, not the rules governing a bonus.
Before treating an offer as having a cash value, check its wagering requirement, maximum bet, eligible games, time limit and maximum cash-out. These terms determine how much play may be required, which bets count, when the offer expires and how much of any resulting balance can be withdrawn. If any condition is unclear, the advertised amount cannot be reliably compared with another offer.
A wagering requirement is a condition on the bonus balance or winnings, not a guarantee that the required play will produce withdrawable funds. The calculation needs to use the exact base specified in the terms. A requirement applied to the bonus amount produces a different obligation from one applied to the deposit and bonus combined. Without that detail, a headline figure has little practical meaning.
Bet limits can affect whether play remains eligible. If a maximum bet applies while a bonus is active, exceeding it may affect the offer or resulting winnings under the stated rules. Game weighting matters too: eligible games may contribute differently towards a wagering requirement, while excluded games may contribute nothing. The label “pokies” alone does not establish that every game qualifies.
Time limits set the period for meeting the conditions. A short expiry can reduce the usable value of an offer, particularly if only certain games count. Maximum cash-out terms set a separate ceiling: meeting the wagering requirement does not necessarily make the full balance withdrawable if a cap applies.
A “no-deposit” bonus is distinct from a bonus that requires a bank-transfer deposit. The phrase describes an offer that does not require that qualifying deposit; it does not establish that there are no wagering, eligibility, time or cash-out conditions. The terms still determine whether any balance can be withdrawn.
There is also a legal constraint that cannot be corrected by favourable bonus terms. Under Australia’s Interactive Gambling Act 2001, operators may not provide real-money online casino games, including pokies, to people physically in Australia. A bank-transfer offer does not alter that position. Accordingly, bonus wording should be read as a description of conditions, not as a reason to use an online casino service.
A conventional bank wire is different from PayID: it is a bank-to-bank payment arranged using the recipient’s account details, rather than a payment sent through an identifier on the New Payments Platform. For a wire, the required information may include the casino operator’s business name, bank name and account number. International transfer details may also call for a SWIFT, BIC or IBAN code.
Banks may allow a wire to be arranged in person at a branch, by phone, or online from a computer or mobile device. The available route depends on the bank and the transfer. Before any payment is initiated, the recipient details need to match the stated business information; a transfer sent to incorrect details can create a separate recovery problem.
Timing is the main cost beyond any fee. A bank wire may take as long as seven business days to appear in an account. That interval is not the same as the time taken to submit the payment: the sending bank, transfer route and receiving account all form part of the process. A pending credit therefore does not necessarily mean that the payment has failed.
Charges may also be higher than those attached to other non-banking payment methods. The total cost can include the bank’s transfer fee and, where an international route is involved, currency conversion or intermediary-bank charges. The amount shown at the casino end may consequently differ from the amount debited.
There is an important legal limit in Australia. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including pokies, to people physically located in the country. A description of bank-wire mechanics is not a recommendation to fund such an account. A payment route does not make the underlying service lawful.
A transfer limit is not a single figure shared by the bank and the receiving service. The bank sets limits on what can be sent from an account, while a receiving operator may apply separate limits to deposits or withdrawals. The amount available in practice is therefore the lower applicable limit, subject to the terms of both parties.
A specialist review has reported bank-transfer maximums reaching tens of thousands of dollars. That figure is not a market-wide standard: limits depend on the bank, account and receiving service, and may change. It should not be treated as a reliable ceiling for a particular transaction. Any comparison needs to distinguish a bank’s transfer limit from an operator’s own transaction cap; they measure different things.
Currency can change the final cost even when the transfer itself attracts no obvious charge. If the bank account and casino account use different currencies, conversion may reduce the amount credited or received. Keeping both accounts in the same currency may avoid or reduce foreign-exchange costs. The relevant comparison is the amount leaving the bank against the amount credited after any conversion, not merely the displayed transfer limit.
These figures do not establish that a particular site is suitable or lawful for Australian residents. Under the Interactive Gambling Act 2001, operators are prohibited from providing real-money online casino games to people physically in Australia. A high transfer cap or a matching currency does not alter that legal position, and neither is evidence of a reliable payout record.
For an Australian resident, the comparison is informational only: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including pokies, to people in Australia. A payment method does not change that legal position.
PayID and a conventional bank wire differ chiefly in settlement time and how the transfer is arranged. A PayID deposit is initiated in a banking app and, where the receiving service processes it, can arrive within seconds; the stated range is 3 to 15 seconds. The transaction limit is set by the bank, so it varies between institutions rather than being a single PayID-wide ceiling.
A bank wire relies on the casino’s business and bank details. It can be arranged at a branch, by phone or online, but a deposit may take up to seven business days to appear in an account. Charges may also be higher than those for other non-banking transactions. That makes a wire a different trade-off: it may accommodate a transfer, but speed and cost are less favourable on the information available.
| Point of comparison | PayID | Conventional bank wire |
|---|---|---|
| Deposit arrival | Typically 3–15 seconds | May take up to seven business days |
| Limit | Set by the sending bank; varies | Depends on the bank and transfer arrangement |
| Charges | No general fee claim applies here | May be higher than non-banking transaction charges |
These timings concern deposits, not withdrawals. A rapid PayID arrival does not establish that a casino payout will be equally quick, and a bank wire’s deposit window should not be read as a payout estimate. Payment speed is therefore only one distinction; it cannot make a prohibited service lawful.
Some sites may offer PayID withdrawals, but a PayID deposit option does not guarantee PayID payouts. Real-money online casino services cannot lawfully be provided to people in Australia.
PayID casino deposits commonly start at AUD 10–20, with some accepting as little as AUD 5. The maximum depends on your bank’s PayID limits; major Australian banks commonly allow AUD 1,000–5,000 per transaction, with daily limits of AUD 10,000–20,000.
At top-rated sites, withdrawal requests for verified accounts are typically reviewed and approved within 2–6 hours. Once approved, PayID payouts may arrive within minutes to hours; the site’s review is often the main source of delay.
PayID casino deposits commonly start at AUD 10–20, although some sites accept deposits as low as AUD 5 via bank transfer.
Created by the ”SpinsUP Casino” editorial team.