Separate operator review from payment delivery, and understand why no-verification claims may still meet identity checks.
A withdrawal has two separate clocks: the operator’s time to review and release a request, and the payment network’s time to deliver the funds. An “instant” label can describe the second clock without saying anything about the first. The total wait therefore depends on the payout method, the operator’s handling, and any conditions attached to the account or transaction.
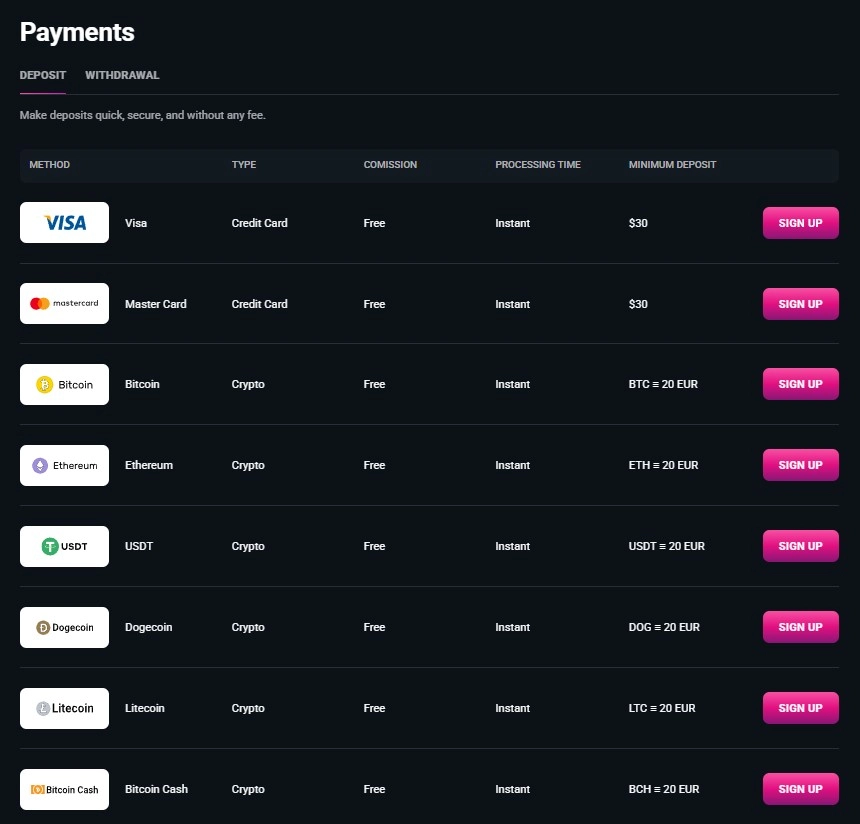
E-wallets such as PayPal and Skrill can move money through a different route from a bank transfer or card refund. E-wallet withdrawals are typically processed by the operator within 24 hours, while bank transfers and card payments may take several days. That processing window is not a promise that funds will appear in the destination account at the same point. A specialist review has described e-wallet transactions as completing within hours rather than days; that is a reported experience, not a fixed service standard across operators.
Traditional bank transfers have a longer possible delivery window. One specialist review reports that a transfer can take as many as five business days to complete. Business-day timing matters: a request submitted outside a bank’s processing window may not move through the same stages as one submitted during it. The operator may also have its own review queue before releasing the payment, so the banking period does not necessarily begin when the withdrawal form is submitted.
A “no ID verification” claim does not by itself establish what checks may apply to a withdrawal. Use this list as a starting point and check the operator’s current requirements before depositing.
Bizzo Casino
Bizzo Casino is listed with a Curacao Gaming Control Board license held by TechSolutions Group N.V.
Vegaz Casino
Vegaz Casino is listed with Curacao license OGL/2024/1335/0780. Its minimum deposit is EUR 20.
Neospin
Neospin is listed with Curacao Gaming Control Board license OGL/2023/176/0095, held by Hollycorn N.V.
Ricky Casino
Ricky Casino lists crypto payouts as taking under an hour and PayID payouts as taking 1–3 business days. The minimum deposit is A$20, or A$30 to qualify for the bonus.
7Bit Casino
7Bit Casino is listed as operating under a Curacao license, with Dama N.V. as operator.
Kingmaker
Kingmaker lists crypto payouts at about 90 minutes and fiat payouts at 1–5 days. Its minimum deposit is A$30.
WinSpirit Casino
WinSpirit Casino is listed with Curacao eGaming license OGL/2024/923/0383, held by Antillephone N.V. Its minimum deposit is A$30.
Playfina Casino
Playfina Casino is listed with a Curacao eGaming license and Hollycorn N.V. as operator since 2017. Its minimum deposit is A$20–30, depending on the offer.
Golden Pokies
Golden Pokies is listed with a Curacao license. No payout speed or deposit details are provided here.
DragonSlots Casino
DragonSlots Casino is listed with a Curacao Gaming Authority license, with Jumpman Gaming Ltd as operator.
Cards have a similar distinction between casino processing and payment-provider handling. A withdrawal may be approved by the operator before it appears on the card account, and card payments may take several days to settle. This route can also be affected by how the original deposit was made and whether a card provider can receive a refund or payout through that channel. Payment availability and withdrawal availability are not automatically identical.
Some real-money platforms described for Australia offer instant-banking services through providers such as POLi. That label concerns the banking connection, not a guarantee that a cashout will be completed immediately from request to receipt. The operator still needs to release the funds, and the receiving bank or payment service still has to process them. A fast transfer rail cannot remove time spent waiting for an internal decision.
The route can also be constrained by the deposit method. Operators generally require funds to be returned to the original payment method where possible. If a deposit was made by one route and the withdrawal is requested through another, the operator may need to apply its payment rules before approving the change. This can affect both the method available for cashout and the time at which the request enters the payment stage.
The amount and account terms matter as well. A per-transaction maximum is not necessarily the only restriction: weekly or monthly cashout limits may apply separately. Where a balance exceeds an applicable threshold, the amount released at one time may be limited by the operator’s policy. A request can therefore be approved for payment without the full balance being sent in a single transfer.
For a no-verification withdrawal claim, the payment rail does not settle the identity question. A fast e-wallet or instant-banking transfer cannot establish that an operator will release a withdrawal without checking the account. Timing claims should be read as descriptions of a particular stage, not as evidence that the entire cashout process bypasses review.
The practical comparison is straightforward: e-wallets have a shorter stated operator-processing window than bank transfers and cards, while traditional transfers can have a longer delivery period. Instant-banking services may shorten the movement of funds after release, but do not control when release occurs. The advertised speed is meaningful only when the operator’s processing time and the payment rail’s delivery time are kept separate.
A promise of a withdrawal with no identity verification confuses two different things: how a service describes its sign-up process and what it must do before releasing funds. A real-money casino cannot process a withdrawal without verifying the player’s identity. The absence of a check at registration, or a label such as “no KYC”, does not establish that the check has been removed. It may simply mean that it has not yet been completed.
For people physically in Australia, there is a further legal distinction. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including slots and table games, to customers in Australia. A claim about a no-verification casino therefore does not make the underlying service lawful or exempt it from identity checks. The phrase describes a marketing claim, not a reliable withdrawal condition.
A specialist review reports that first withdrawals often prompt identity-verification requests. That timing is consistent with the difference between opening an account and asking an operator to release money: a withdrawal makes confirmation of the account holder directly relevant to the transaction. A request at that point is not proof that verification was waived earlier. It may be the first stage at which the operator has required it.
The important distinction is between a check that has not yet been requested and a check that will never be required. Those are not equivalent. A service may allow account activity before asking for documents, while still placing a withdrawal on hold until identity checks are complete. In that situation, “no verification” describes the earlier account stage, not the conditions for receiving funds.
The cashout process also has a different consequence from ordinary account access. If verification is outstanding, the request cannot move to payment release until the operator has completed the required check. The payment method does not remove this requirement; a faster transfer rail cannot settle an identity review that remains open. “Instant” can describe only a payment phase after approval, not the entire route from request to receipt.
Completing identity verification before a first withdrawal can significantly speed up future withdrawals. The practical gain is procedural: when the account has already passed the identity check, a later request is less likely to be delayed by that same unfinished step. It does not mean every later cashout will be automatic or immediate. It means one avoidable point of uncertainty has been dealt with in advance.
That distinction matters when comparing “no ID verification” claims. An account that has not yet been asked for documents may look simpler at the start, but the unresolved check can become a condition at the moment funds are requested. An account verified early has completed that part of the process, although the operator still determines whether any other review applies. The useful comparison is not the number of screens at registration. It is whether identity approval is complete before a withdrawal is submitted.
A sound reading of the terms separates three stages: account creation, identity review and withdrawal release. A claim about the first stage says little about the second. A statement about fast payment says little about the third unless it specifies that the operator has approved the request. If those stages are presented as one uninterrupted “instant withdrawal”, the wording conceals where a pause can occur.
“No verification” should not be treated as a guarantee that no documents will be requested. The more defensible interpretation is narrow: the service may not require a check immediately. Before relying on any withdrawal description, the relevant terms should make clear whether identity verification is required before funds can be processed and what conditions apply to approval. If the wording is silent, silence is not evidence of an exemption.
There is little financial value in an apparently simple registration if an unfinished check prevents the balance from being released. The calculation is straightforward: early verification may add a step before a withdrawal is needed; postponing it can leave that step outstanding when the withdrawal request is already waiting. Completing it in advance can reduce that avoidable delay on later withdrawals, without changing the operator’s broader review authority.
Accordingly, a no-verification claim and a verified account are not interchangeable descriptions. The first may refer to when a check is requested. The second describes a check already completed. For withdrawal purposes, the latter is the more relevant condition; neither wording alters the legal prohibition on providing real-money online casino services to people in Australia.
A displayed balance can combine deposited money, promotional credit and winnings, but those components may not have the same withdrawal status. The figure on screen is therefore not, by itself, the amount available for cashout. Where a promotion carries wagering conditions, its terms determine what must happen before funds associated with it can be withdrawn.
The key distinction is the base used to calculate the wagering requirement. A specialist review describes two possible structures: wagering may apply to the bonus funds alone, or it may apply to the combined deposit and bonus. The first is preferable because the amount that must be wagered is calculated from a smaller base. That does not make the bonus cash, remove other conditions or establish that a withdrawal is available as soon as the bonus is credited.
Consider the accounting in general terms. With a bonus-only requirement, the qualifying play is measured against the promotional amount. With a combined-balance requirement, the deposit is included in that calculation as well. The deposit may therefore be tied to a promotion even though it was not itself promotional credit. The practical difference is not cosmetic: the same bonus can create a different withdrawal hurdle depending on which base the terms specify.
The relevant wording is usually found in the promotion’s conditions and the account’s bonus or wallet display. It should identify whether the deposit is included in the wagering calculation, which activity counts, and what happens when the conditions have not been completed. A headline describing a bonus does not settle those points. Nor does a large displayed balance: it may represent a mixture of cash and restricted funds rather than a single withdrawable sum.
A useful way to assess the offer is to separate its stages. First, identify the amount credited as a deposit and the amount credited as a bonus. Next, establish which of those amounts forms the wagering base. Then determine whether the resulting requirement has been completed and whether any further stated conditions remain. Only after those checks can the balance be treated as eligible for withdrawal under the promotion’s rules. This is a terms calculation, not an inference from the account’s total.
Assessing Bonus Balance
Identify funds
Separate the amount credited as a deposit from the amount credited as a bonus.
Establish the base
Determine if the wagering requirement applies to bonus funds alone or the combined deposit and bonus.
Verify conditions
Check if the resulting wagering requirement has been completed and if other stated conditions remain.
No-deposit promotions and free-spin offers require the same distinction. A promotion that does not require a deposit may still attach conditions to the bonus or to winnings generated from it. Free spins may produce a credit that is subject to the offer’s rules rather than cash that can be withdrawn at once. The absence of a deposit changes the starting point; it does not, on its own, establish that the resulting balance is unrestricted. The relevant terms must say how winnings are treated and what conditions apply before withdrawal.
The word “free” has little accounting value without that detail. If a bonus is subject to wagering, the amount shown after crediting it cannot be assumed to be the final cashout amount. If the requirement is based on the combined deposit and bonus, deposited funds may also remain unavailable while the promotion is active. If the requirement is based on bonus funds alone, the deposit is not part of that specific calculation, although other conditions may still govern the account. These are materially different arrangements, even when the promotional headline looks similar.
The same scrutiny applies to offers presented as easy to claim or requiring only an email or text confirmation. Those descriptions concern access or account steps; they do not explain the wagering base or make promotional credit withdrawable. A claim of no verification does not answer whether bonus conditions have been met, and a simple sign-up process does not replace the written rules. The decisive question for the balance is what the promotion requires before funds can leave the account.
For customers physically located in Australia, there is also a separate legal limit: real-money online casino games, including slots and table games, are prohibited services for operators to provide under the Interactive Gambling Act 2001. A bonus description does not alter that status. Where promotional terms are being assessed, the distinction between bonus-only and combined deposit-and-bonus wagering remains an accounting distinction, not an endorsement of an offshore casino offer.
The sound comparison is therefore not between headline bonus amounts. It is between the stated wagering base, the conditions attached to the resulting balance and the point at which the terms permit withdrawal. Without those details, a promotional credit is only a conditional entry on an account—not cash available to take out.
A cryptocurrency payment can reduce the amount of ordinary banking information visible in a transaction, but that does not make an account anonymous. A wallet address is not the same thing as a verified identity, and a payment record does not replace the checks an operator may require. The distinction matters because searches for a crypto casino with no identity checks often combine two separate claims: privacy at the payment stage and permission to withdraw without being identified.
Neither follows automatically from the other. A blockchain transaction can be traceable, while an operator can connect a deposit address or account activity to a customer profile. An account may also be subject to identity checks independently of the payment method. Choosing Bitcoin or another cryptocurrency therefore does not establish that a withdrawal can be made without documentation, nor does it guarantee that a payment will remain private from the parties involved in processing it.
A specialist review describes cryptocurrency transactions as potentially near-instant. That characterises the transfer rail, not the entire cashout process. The casino must first accept and release a withdrawal; any internal review, account check or transaction condition can add time before funds are sent. After release, the receiving wallet and network still matter. The word “instant” is useful only when the stage it describes is stated. It does not mean that a withdrawal request moves from submission to usable funds without intervening steps.
The same separation applies to other payment methods. A specialist overview of payment options for Australian-facing casino services lists cards, PayPal and Skrill e-wallets, bank transfers and, at some operators, cryptocurrency. That is a description of methods reported in the market, not confirmation that a real-money online casino is lawful or available to people in Australia. Under the Interactive Gambling Act 2001, operators are prohibited from providing online casino games, including slots and table games, to people physically located in Australia. Payment options advertised by an offshore service do not change that legal position.
Cards require particular care. Although payment comparisons may group credit and debit cards together, they are not interchangeable for online gambling. Credit-card payments for online gambling services are not permitted. A reference to a card option should not be read as approval to fund an online casino with credit. Debit cards appear in descriptions of payment methods, but their presence on a payment page does not establish that the service itself is lawful for Australian customers.
This is also why “no verification” is a poor measure of payment privacy. A service might let an account be created or funded before requesting documents, yet still require identity information when a withdrawal is sought. A cryptocurrency deposit does not override that requirement. Nor does a wallet transaction establish that the person requesting a payout owns the account or is entitled to receive its funds. Privacy at one point in the transaction is not a substitute for account verification.
The practical comparison is therefore not simply crypto against cards. It is the information exposed through a payment method, the rules that govern the service, and the checks attached to the account. E-wallets such as PayPal and Skrill, bank transfers and digital assets each involve different payment records and intermediaries. None should be treated as a guarantee that the customer’s identity is hidden from an operator or that a withdrawal will be approved without review. A payment method can change how money moves; it cannot make a prohibited service lawful or erase the operator’s responsibility to verify an account.
Bitcoin searches often assume that a wallet address functions like cash: transferable, detached from a name and therefore sufficient to avoid identification. That conclusion confuses pseudonymity with anonymity. A public transaction record may be associated with an address rather than a person’s name, but the address can still be linked to account details or other records. The available payment method is only one part of the information trail, and it says nothing conclusive about what checks an operator will apply.
For Australian residents, the legal context comes before the payment comparison. Online casino-style services—including slots, poker and table games—are prohibited when offered to people in Australia. Offshore payment pages, cryptocurrency acceptance and claims about private transactions do not remove that restriction. Nor should a claim of no identity checks be taken as evidence that the service can lawfully provide casino games to Australian customers.
The financial distinction is straightforward: a fast transfer is not an anonymous account, and a private-looking payment is not a withdrawal exemption. Cryptocurrency may move funds rapidly at the network stage, but speed, privacy and identity verification are separate properties. Combining them into a single promise of a no-verification cashout leaves out the conditions that determine whether a withdrawal can be processed at all.
A deposit method and a cashout method perform different jobs. A voucher can put money into an account without providing a route for money to come back out. That distinction matters for searches about no-verification pokies or slots: a quick way to fund an account does not establish that a withdrawal can be made without identity checks, or that it will arrive quickly.
Prepaid cards and vouchers, including Neosurf, are described in specialist reviews as deposit options that generally do not support withdrawals. The balance may therefore need to be paid out through another method accepted by the operator. The available route depends on the account’s payment rules; a voucher should not be treated as a two-way wallet merely because it was accepted at deposit.
That changes the practical calculation. The deposit can be recorded promptly, while the withdrawal still depends on the operator’s approval and the payout rail. Where a voucher cannot receive funds, the time taken to buy or redeem it says nothing about the time required to receive a cashout. “Instant” at the deposit stage is not a measure of the complete withdrawal process.
For an account funded by voucher, the first check is whether the operator permits withdrawals to a different payment method and which methods are available for that account. Payment rules may require funds to return to the original method where possible. If the original method cannot accept a payout, the operator may specify another route and require the receiving account to be linked to the player profile.
That is not a minor administrative detail. A withdrawal request directed to an unsupported payment method can be delayed while the route is corrected or reviewed. The posted payment terms should explain the permitted methods, any fees and limits, and the operator’s processing procedure. A deposit screen alone does not supply that information.
For routes that can receive withdrawals, the delivery period varies. E-wallet payouts are described as commonly being processed within a day, whereas card payments and bank transfers can take several days. Those periods do not necessarily begin when a withdrawal is requested: the operator may first need to review and release it. After release, the receiving payment provider or bank controls the next stage.
Typically processed by the operator within 24 hours and often completing within hours.
Can have a longer delivery window, with some reports taking as many as five business days.
May take several days to settle after the operator has approved the withdrawal.
This is why a claim of a no-verification instant withdrawal should be read as two separate claims, not one. “Instant” might refer to the payment movement after approval; it does not establish that approval is immediate. And an account’s deposit route does not remove the casino’s identity-check requirement before a withdrawal is processed. A payment method can reduce friction at one stage without changing the checks or timing at another.
A voucher’s principal function is to transfer a deposit value into an account. It may offer a way to pay without entering bank details on the deposit page, but that does not make the account anonymous or exempt it from identity verification. Payment privacy and identity checks are different questions.
The same point applies to “no deposit” wording. A promotion or account balance does not itself demonstrate that a cashout is available: withdrawal eligibility depends on the applicable account and payment conditions. Any wagering conditions attached to funds must be satisfied before a withdrawal can be attempted. The balance shown on screen is not necessarily the amount currently eligible for payout.
For slots or other casino-style games, the underlying game does not determine which payment rail can receive a withdrawal. The relevant mechanics remain the payment method, the operator’s approval, and the receiving provider’s processing. A voucher-funded balance does not become withdrawable through that voucher merely because it was used to play.
There is also a legal boundary specific to Australia. The Interactive Gambling Act 2001 makes it illegal for operators to provide real-money online casino games, including slots, to people physically located in Australia. A description of payment mechanics is not an endorsement or offer of access to those services.
The practical distinction is straightforward: a deposit method establishes how funds enter; a payout method determines how approved funds can leave. Where prepaid vouchers are accepted for deposits but not cashouts, the withdrawal must follow a separate permitted route, with identity verification completed before processing. A fast deposit is only the first transaction in that chain.
A request to avoid a phone call is not the same as a request to avoid identity checks. Phone verification is one possible contact step; Know Your Customer (KYC) checks concern who owns the account and whether the withdrawal can be released. A service that does not ask for a call may still require identity documents or other checks before paying out. No-phone wording changes the contact method, not the verification obligation.
This distinction applies whether the account is used for real-money pokies, table games or a live dealer feed. The game format does not create a separate route around KYC. A withdrawal is a transfer of funds from an account, so the operator has to establish the customer’s identity before processing it. A live stream, faster account registration or a deposit accepted without documents does not establish that identity.
First withdrawals often prompt an identity request, according to specialist reviews of casino procedures. That timing can make the check seem like a new condition introduced at cashout. In practice, the deposit stage and withdrawal stage are different control points: an operator may let an account be opened or funded before it has completed its checks, then require evidence before releasing funds. The commercial distinction is simple: an account balance is not a paid withdrawal.
Phone checks should therefore be read narrowly. A platform may not call, but it can still pause a withdrawal while it checks documents or account details. Conversely, providing a phone number does not prove identity on its own. The relevant question is what KYC evidence is required, how it must be submitted, and whether the account details match the person making the withdrawal. A “no phone verification” description cannot answer those points.
The same logic applies to claims that a real-money service needs no verification at all. Such wording may describe registration, deposits or a particular stage of account use; it does not override the requirement to verify identity before a withdrawal is processed. If a site accepts funds without checking documents first, that only shifts the point at which the check occurs. It does not remove the check.
There is also a legal limit to how these services can be described in Australia. Under the Interactive Gambling Act 2001, operators are prohibited from providing real-money online casino games, including pokies, poker and table games, to people physically located in Australia. Casino-style games are treated as prohibited interactive gambling services in this context. A page should not present an offshore real-money casino as an available Australian service or suggest that bypassing KYC makes one lawful.
For any account already in use, the practical record to assess is the operator’s written verification policy: which documents are requested, whether further checks may follow, and what happens if submitted details do not match the account. The account holder’s name and payment-account details should be consistent with the casino profile; mismatches can invite additional scrutiny. Submitting incomplete or inconsistent information does not turn a pending check into an approved withdrawal.
A claim of “no verification needed” is therefore not a reliable measure of how quickly funds become accessible. It may signal that checks are deferred, or simply describe a limited part of registration. The outcome that matters is whether the operator has completed KYC and approved the withdrawal. Without that approval, the funds remain on the account regardless of whether the game was a slot or a live-casino table, and regardless of whether any phone call took place.
PayID is Australia’s bank-to-bank payment system, operating through the New Payments Platform (NPP). Its real-time transfer function applies to the movement of funds between accounts; it does not determine when a casino approves a withdrawal request.
The process has separate stages: the operator receives the request, checks it, and releases the payment. Only then can PayID’s transfer speed matter. A request may wait for identity verification, account checks, or a review under the operator’s terms. A “no verification” claim does not remove the requirement for identity checks before a withdrawal can be processed.
The PayID details should match those used for deposits, and the destination account must be linked to the casino profile. A mismatch can prompt additional review rather than a faster payout. The amount requested must also comply with the operator’s withdrawal rules; fees and limits may affect the final amount received. Any applicable bonus wagering conditions must be completed before funds are eligible for withdrawal.
Some specialist reviews report withdrawals at selected PayID casinos being processed in under five minutes, compared with one to three business days for standard bank transfers. That comparison describes reported operator performance, not a guaranteed interval from request to receipt. Internal approval remains a separate step, and transfer speed begins only after release.
The relevant figure is therefore not just the payment rail’s speed. It is the full sequence: eligibility, checks, approval, and transfer. PayID can make the final stage near-instant without making the entire cashout immediate.
They are casinos that make cashouts straightforward and process them quickly, with clear limits and convenient payout methods. A fast payment method does not remove identity checks, which may be requested before a withdrawal is released.
Check the operator’s processing time separately from the payment method’s delivery time, and look for clearly stated withdrawal limits and fees. Confirm that your preferred method supports withdrawals and complete identity verification early to help avoid delays.
PayID withdrawals can arrive in seconds or minutes once the casino releases them, while e-wallets are typically processed by the operator within 24 hours. Bank transfers and card payments may take several days, and traditional bank transfers can take up to five business days.
Options include credit and debit cards, PayPal and Skrill, bank transfers, and, at some casinos, cryptocurrency. PayID and POLi instant-banking services are also offered by some sites; prepaid cards and vouchers such as Neosurf are usually for deposits rather than withdrawals.
Prepared by the SpinsUP Casino editorial staff.